Friday, 31 January 2020

Market Structures in Services

Services have long been thought to suffer from a productivity problem. In fact, there is a long-standing concern that services add little to the economy. Particularly compared to manufacturing, which is typically more receptive to technological improvements, services productivity looks bleak.

What’s more, for various technical reasons a natural tendency exists in many OECD economies for services to expand as these countries become richer.

This creates a double whammy: if productivity in services are low to start with, plus a natural expansion of services exists in many rich economies, then ultimately the sector becomes a real drag on overall economic growth the richer we get. That’s the long-held view.

However, this view becomes increasingly debunked. A new report that ECIPE has developed, which was commissioned by the Bertelsmann Foundation, now shows that not all services are unproductive. In fact, some services show healthy productivity growth patterns.

Therefore, good evidence is starting to come up proving the point that services do not need to weigh down on the economy. On the contrary, there is enough potential for services to perform better. The truth is that there is a lot of productivity in many services sectors that remains unrealized.

What can explain this? For one, our study shows that the low pick-up of digital technologies by services firms is an important factor to blame. For instance, using Eurostat data, the report shows that the share of business services firms in the UK and Poland that pick up digital technologies (as measured by our self-developed E-business indicator) is only half the rate of Denmark and Finland, as shown in the figure below.

Tuesday, 17 September 2019

China’s Digital Trade Success: Two Different Perspectives

In recent times there has been a lot of talk on how big China’s digital trade actually is and to what extent it poses a threat to the global economy. China is big and appears successful in digital trade, and therefore the logic goes that China is leading the field. Others are more careful in cheering China’s digital success. The truth, however, is that there are two versions to the story. One is centred around the fact that China is indeed big. The other focuses on the extent to which China is actually competitive. The two stories are connected, yet extremely different. 

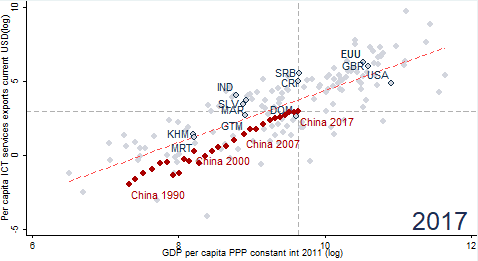
Both narratives are respectively illustrated in panels A and B below.

Panel A shows what I call the political story. This story reflects the fear of China becoming the biggest digital trader in the world. The panel shows digital services exports on the vertical axis (in USD log scale to compile the pattern) while showing the level of development (in USD PPP) on the horizontal axis for the year 2017. I take digital services and not digital goods for two reasons: One is that services reflect the future of digital trade; two is that the pattern for digital services and goods is the same, so analysing both would merely be repetitive. (There is one big difference between digital services and goods which I will address later).

First things first though, an upward sloping line appears on the vertical and horizontal axes in Panel A. It means that countries that progressively become richer also become more successful digital services exporters. How that works doesn’t matter for now. What matters is that the two indicators are tightly connected. Countries such as the US and the UK are much more developed and have greater levels of digital services exports; unlike Cambodia (KHM) or Mauritius (MRT).


Panel A: China is big and will continue to grow bigger in digital services trade…


Panel B: But China is uncompetitive and is likely to remain so in digital services trade.

Source: Author's; WB Development Indicators.

The remarkable thing about China, is that it has been a big digital trader throughout history, and is likely to remain so. That can be seen by the red dots which denote China from 1990 till 2017. At any year, China was a far bigger digital exporter than any country with a similar level of development. For instance, in 2000 China’s level of development was equal to Cambodia’s level of development today, i.e. in 2017. Yet China’s export in digital services were already bigger back then, than Cambodia’s is right now.

What’s more remarkable, however, is that China has caught up incredibly quickly with the world’s biggest digital traders. Panel A shows that since the 1990s China has steadily approached the EU, US and UK. All three are richer and have also historically shown a high level of digital services exports. But China, standing at a lower level of development, has managed to increase its export capacity in digital services, to a level in 2017 where it reached a par with the UK. The EU and US are still bigger digital traders, but it will only take about another 10 years before China reaches an equal footing with these two trade giants.

That has repercussions in the political sphere, particularly when negotiating trade deals. Bigger countries naturally have more weight in trade negotiations. However, they do not always naturally have a bigger trade basket, as they have bigger domestic markets which they can rely on. China’s case is different, as it has traditionally used trade as a successful strategy for economic development. Today the EU is still the biggest exporter of digital services, ahead of the US and China. It therefore currently has the biggest heft when negotiating digital services trade issues; far bigger for instance than the UK will ever have.

In short, the political economy discourse about the “fear” of China’s digital trade success, which one can read daily in the popular media, stems in great part from the sheer size of the country. Don’t get me wrong, size does matter, and it certainly makes a difference on how successfully countries like Guatemala or China can negotiate in trade negotiations. For instance, China has been a big trader in the past of ICT or high-technology goods. Indeed, at all levels, it has been a bigger trader in digital goods than all other countries, including the EU and US (Panel C). As such, China has influence on international digital trade negotiations.

However, there is another perspective on the matter, which I call the economic story. That story is reflected in Panel B. Economists have always been sceptical of the idea of using plain magnitudes expressed in nominal or absolute numbers. Rather, economists tend to transmit their messages in “normalized” numbers, so that any form of size, quantity or volumes are instead computed as ratios, weights or proportions. The big reason for doing so is that otherwise numbers may be biased in favour of other characteristics, such as in our case the huge size of a country. After all, China may be big, but that may not tell us anything about its true economic success.

Panel B investigates how competitive China is once we disregard its sheer size. Note that I again analyse digital services trade, as my view is that this is where the future of trade is heading. Interestingly, using similar metrics as in Panel A, the story gets reversed. To correct for China’s size when using its nominal numbers of digital service exports, I divide this variable by its population.

Through that way I obtain a more neutral representation of the true extent of China’s export success, which economists typically call the per capita exports. It’s a much fairer way of comparing China with other countries, as smaller countries trade a much smaller amount. Once we divide the absolute size of digital services exports by the number of people in each country who potentially trade, an undistorted picture of the true strengths of digital trade exports is presented. In other words, it shows the real digital export competitiveness.

Looking at Panel B, it becomes clear that China’s real digital trade competitiveness is actually much lower compared to using non-normalized trade figures. In fact, the red dots that denote China’s development over time, are all placed below the dashed fitted values line, which represents the “average” trend between how rich countries are at a certain level and their per capita digital services exports. Compared to other countries, China is less competitive in digital services exports than can reasonably be expected based on its level of wealth.

That was true in the past and is true in the present. For instance, back in 2000, when China shared a similar level of development as Cambodia today, the latter exported more digital services when the size of the market was accounted for. Similarly, in 2017, Guatemala was able to export more digital services on a per capita basis than China did in 2007; when the two countries shared a similar level of economic development. Today, China is as rich as Serbia or Costa Rica, but the two latter countries are far more competitive regarding digital services trade, given their rate of economic development.

What’s more, there are little signs that China’s competitiveness position is approaching any average midpoint value (dashed line), based on what could be expected when taking into account the level of development of all other countries in the sample. Nor does China approach the competitiveness position of the EU, the UK or the US. (Note that the US suffers from a relatively low level digital services export competitiveness, meaning that for whatever reason the country is performing below its potential given its already massive success.) In fact, the EU is in a pretty good shape as it is placed above the fitted values line – although several other countries are doing much better still.

So, what should the conclusion be when putting these two panels together? Well first, one big message from this exercise is to show that one shouldn’t conflate size with “real” size. Yes, China may be big, and the economic size of China may disturb us from time to time, but it’s another thing to claim that because of its size the country is going to be a giant success in all manners of our digital life, and take over the digital world economy. Sure, China has success in some parts, and perhaps many parts of the digital economy, but not in all parts. In goods, the country is a major success, and so too it seems in digital goods (compare panels C and D in the annex). However, for digital services the story is a different one.

Second, the fact that China is precisely less competitive in services has implications for future trade. The world economy is increasingly shifting into an invisible one in which services, data, technology ideas and know-how are replacing goods, commodities and other physical inputs. In this intangible world, China appears to be far less successful compared to other big trade giants. Moreover, China is also very restrictive when it comes to digital trade, data and internet technologies. Different digital standards and restrictive digital policies, such as China has today, are harmful for its digital services trade and eventually real export competitiveness (Ferracane and van der Marel, 2018).

Therefore, it remains to be seen whether China’s isolated stand regarding data and the internet will prove to be beneficial for improving its export competitiveness the long run. 


Panel C: China is big and will continue to grow to be the biggest in digital goods trade…


Panel D: And China is competitive and is likely to remain so in digital goods trade.

Source: Author's; WB Development Indicators. 

Wednesday, 5 June 2019

Solving EU’s Amazon Paradox

Here's a question for you. 

I recently attended a seminar about Europe’s digital future where I was asked: “How come we have the Amazon Paradox in Europe?”. To explain, the Amazon Paradox involves the package delivery time between EU member states that is excessively long compared to the US. In short, if I want to send a package from Brussels to say Sofia, it travels for up to 8 days, whereas in case I would send it to the US, it only takes 2 days.

How is this possible? That was the question. To give context, the seminar itself was about Europe 4.0. It discussed the way in which Europe can be made more competitive through the use of new digital technologies. The automatic response to the question was that many European countries still uphold digital trade restrictions. Given that Amazon is an online platform, it must be that digital trade restrictions such as strict intermediate liability regimes or data policies are the culprit. Right?

After all, our own research showed that several restrictions regarding e-commerce platforms are still relatively high for some EU member states. Of the 64 countries analysed worldwide, European countries such as France, Germany and Italy show a level of restrictiveness that is placed above average. So, the problem of delayed package delivery in Europe must surely have something to do with these restrictions.

As a matter of fact, I don’t think so. Yes, Amazon is a digital platform and it may encounter some digital barriers, perhaps even in some digital services such as digital finance, but my assessment is that the bulk of the package delivery problem lies somewhere else, namely in Europe’s network services.

Accessing Amazon’s website and order something does not seem to me any problem. What’s more problematic are all the services that lie behind the internet transaction. The package needs to travel from one destination to another. It is most likely to use postal delivery services or any other transport and storage services. That’s exactly where the bottle neck seems to appear. In many European countries, these network markets are still largely uncompetitive.

A simple snapshot of some OECD numbers is telling. The picture below gives a screenshot of the OECD’s Product Market Database that records the level of non-digital regulatory restrictiveness in network services. The message from these numbers is quite interesting. For instance, although the market for postal service is entirely free for new firms to enter, which gives the impression that competition is optimal, the yellow column indicates that public ownership restrictions are still rampant.


Restrictions on public ownership includes the extent to which State-Owned Enterprises (SOEs) are still present in the postal market, how much governments are generally involved with the operations of the postal incumbent firm, or whether they have a direct control over the postal services company. Restrictions in this field also relate to how these SOEs are governed. For instance, whether the state or provincial governments have special voting rights (e.g. golden shares) in at least one firm.

The scoring of this restrictiveness index ranges between 0-6, with increasing levels indicating higher levels of regulatory barriers. Looking at the yellow column, it becomes clear that many European countries have a level of restrictive regulations in the postal market that stands at 5. True, numbers are from 2013 (latest year available), but nothing suggest that all these countries have quickly reformed their markets over the last couple of years. Similar conclusions are true for rail transport services.

The European Commission is also very aware of the issue. As stated in a recent report that was commissioned by its in-house staff: “One of the core objectives of the EU’s Digital Agenda is to promote cross-border e-commerce…” The report continues: “The Commission identified expensive and unreliable cross-border delivery as one key challenge in the future development of e-commerce”. Auch!

Another report commissioned by the European Commission states the problem in clear numbers. It looked at the price differences between what it would cost to send a package within and across EU members states. And guess what, this differential price in package delivery is equal to a factor of 3.71. This comes down to an average price difference of 471 percent for packages sent to another country in the EU compared to sending domestically. 

In short, these numbers point out that the international postal market delivery services are still largely uncompetitive. I think that this is the main driving force behind Europe’s Amazon Paradox. With price differences so high, it reflects that the market suffers from a lack of competitive forces from which indeed e-commerce companies like Amazon encounter a paradox: although the distance to the US is larger, package delivery is faster. 

Friday, 18 January 2019

Online Platform Restrictions and Small Firm Exports

Stricter rules on online platforms restrain potential trade, especially for smaller businesses. This is because online platforms facilitate export and import by lowering transaction and information costs. Ultimately, restrictions on online platforms limit the capacity of the ICT sector more generally to contribute to the overall economy.

A recent study by McDaniel and Parks (2019) shows that, among those businesses that export, the share of firms using Facebook can be high for some countries. For instance, in Czech Republic, Portugal, Turkey, and South Korea more than 15 percent of businesses that export are also on Facebook. This share is even higher for small and medium sized firms (SMEs). Therefore, it seems that the use of online platforms such as Facebook creates a stronger propensity to export compared to other firms.

Once a firm finds itself on a digital platform such as Facebook, its presence can help to create visibility and to capitalize on the platform’s online network, eventually reducing information and search costs for companies and consumers. According to the study, some developing countries profit the most from being present on Facebook. In Bangladesh and Pakistan, for instance, 20 and 18 percent of businesses that export are also present on this social app.

However, to make use of online platforms is not always an easy task. Certain policies inhibit companies from accessing online platforms, especially foreign ones. These policies often create unnecessary costs for businesses, particularly for smaller firms as they make it difficult to intensify exporting abroad. Moreover, and perhaps even more importantly, the presence of online platforms themselves is not a given in some countries reducing the ability of small firms to promote their businesses online in the first place.

This phenomenon is a problem if we consider an increasingly strict regulatory environment for online platforms. In a recent study by me and my co-author Martina Ferracane, we show that this is actually true for quite a number of countries.

The study maps the regulatory environment for online platforms in terms of trade restrictiveness for 64 countries. More precisely, we measure the online platform trade restrictiveness using the information available in the Digital Trade Estimates database, from which we have already developed the Digital Trade Restrictiveness Index (DTRI). By selecting only those policy measures that affect online platforms and by finetuning the methodology, we have created the Digital Platform Restrictiveness Index (DPRI).

Thursday, 13 December 2018

Productive services with the help of internet technologies.

See here my new piece for the Asian Development Bank Institute's blog: Productive services with the help of internet technologies: https://bit.ly/2rzBOZB

It's about how new digital technologies can "cure" the long-standing concern of services suffering from low productivity growth. That's not longer a necessary development.

Yet, to let new digital technologies do what's best to make services more productive, policies need to be set right. Read the blog for why and how that can be done. 


Monday, 12 November 2018

Global Value Chains and Digital Trade Restrictions Part II

Last month, I wrote about how digital trade restrictiveness of countries is associated with how much countries participate in Global Value Chains (GVCs). This follow-up column explains how digital trade restrictions are also strongly associated with where countries participate in GVCs.

In another blog post, I made clear that the use of ICT in GVCs is unrelated with the complexity of value chains. Instead, ICT-intensity of GVCs relates better with the relative position of industries in value chains. That is, where industries are most active in GVCs. In fact, industries closer to consumers are often industries that are also relatively more ICT-intense. They are placed more downstream. Vice versa, industries that are more upstream often appear less ICT-intense.  

Now, this pattern is also reflected with regards to countries’ digital trade policy framework: countries that are less restricted across the whole range of digital trade policies are more active in supply chains that are closer to the final consumer, i.e. more downstream. On the other hand, countries that are more restricted with digital trade policies are often trading more in upstream value chains, being further away from final consumers.

This can be seen in the figure below. The vertical axis plots a measure of the relative position of countries in their supply chains. Higher values on this indicator means higher GVC “upstreamness” of countries, trading more in GVS that are more upstream. The horizontal axis plots ECIPE’s Digital Trade Restrictiveness Index (DTRI) with higher values reflecting greater digital trade restrictiveness. 

The graph shows that countries such as Indonesia, India, Brazil and Turkey are more restricted regarding digital trade policies whilst also trading more upstream in GVCs. Contrary, countries which are less restricted in digital trade policies are trading more downstream in their supply chains. They are closer to the final destination of the good (or service), i.e. the consumer.


Source: ECIPE; COMPNET

Thursday, 18 October 2018

Global Value Chains and Digital Trade Restrictions Part I


Today, I gave a talk at Bruegel’s Asia Europe Economic Forum (AEEF) on Global Value Chains (GVCs) and restrictions on the use of digital technologies across borders. It was part of a panel session that was dedicated to GVCs and the 4th Industrial Revolution. It was a great opportunity to connect our Digital Trade Restrictiveness Index (DTRI) with that of GVCs.

The underlying question of my presentation was: How much of an important factor are digital trade restrictions for GVCs? As it turns out, a lot!

When talking about the 4th industrial revolution, we often talk about many different concepts such as Artificial Intelligence (AI), Internet of Things (IoT), big data and cloud computing. One commonality these technologies have is the use of data over the internet. The figure below shows which sectors in the economy use a lot of data, and are therefore intense in the use of digital technologies.

Interestingly, besides many services that are data-intense, some advanced GVCs are in fact also very data-intense (something I referred to in February this year in another blog post). Computer electronics, Machinery, Chemicals and Motor vehicles are sectors that thrive on GVC networks and the figure shows that these sectors are also very data-intense by using lot of digital technologies. 


Now, how do digital trade restrictions come into the story? The answer is simple: as these GVC sectors use a lot of digital technologies, digital trade must surely be a factor of importance of how competitive such sectors can be. After all, open markets provide firms with the best available technologies through competitive goods and services, and thus also competitive digital goods and services.

That’s indeed the case. That becomes visible in the following figure. In there, the DTRI is plotted on the horizontal axis, measuring the restrictiveness in digital trade for a host of countries; whilst the vertical axis plots a measure of GVC participation, which is nothing else than an advanced indicator that measures the extent to which countries show more or less trade in GVCS.

As we slide along the horizontal axis from left to right, we see that countries which are more restricted are also showing a lower participation in GVC sectors. Conversely, if we move along the horizontal axis from right to left, we see that countries with lower levels of digital trade restrictions precisely have a higher level of GVC participation. Therefore, digital trade restrictions really seem to matter for participating and being competitive in GVCs. 


There was more in my presentation that warrants another blog post. But one thing I would like to tell is that besides how much a country participates in GVCs, digital trade restrictions also appear to matter a lot for where countries are active in GVCs. So not only do digital trade restrictions matter how much a country capitalizes on GVCs, but also where in the supply chain they are active.

As it turns out, they are precisely active where services come in. But that’s for a second blog post later on. 

Tuesday, 4 September 2018

Inclusive Growth and Policy Reform

Recently, the first joint conference between the IMF, OECD and World Bank was held which discussed topics related to structural reforms.

At this conference, recent research on the linkages between product market regulations and inclusive growth were presented. The conference brought together policymakers and practitioners, international institutions, and leading academics to discuss key policy issues in the area of product market competition and regulation and growth.

One of the research papers was joint work I did with Mariana Iootty (World Bank) and Janez Kren (Leuven University). See below for slides. In there, we analyze how services regulations have had a positive impact on productivity developments in the EU. Interesting fact is that a lot of behind-the-border regulations on how firms operate, as opposed to pure entry barriers, have a particularly strong effect on productivity. 


This is an important finding. Of course, entry barriers still matter for letting services firms enter a closed market so as to bring in more competition resulting in lower prices for those industries that use a lot of services, mainly as inputs. This ultimately translates into greater bang for the buck, which in economic terms is called stronger a productivity level and and eventually growth. 

However, as said, not only entry barriers matter. Once a company has entered the market, it still faces a hurdle of additional regulations which can actually frustrate firms to grow bigger. This growth of firms is an important supplementary force for greater productivity. Markets free from burdensome regulations allow firms to reach greater scale, that in turn forms an extra knock-on effect on productivity.

Many EU countries have over the years come to decrease their entry barriers, but in some cases barriers on the operations (or conduct) of the firm are still there. In other instances countries have in recent years actually increased their regulatory burdens for firms, which precisely are found in these behind-the-border barriers on operations. 

Time to be alert, therefore!


Thursday, 7 June 2018

What Digital Policy Restrictions to Focus on?

Now that the DTRI is out, I have received the same question various times from different policy officers in the field: what digital policy restrictions should we focus on?

The DTRI covers a wide spectrum of policy categories ranging from tariffs in ICT goods to regulations in services and investment to cross-border data flows restrictions. The obvious answer to a trade economist like me would therefore be: well it depends. That’s a cliché, but since economics is about scarcity, decisions need to be made about trade-offs.

Personally, I am more interested in the future of trade, namely (digital) services, data and ideas and other intangibles. I think that’s where world trade is heading to and where new large productivity gains will have to come from. That’s not to disregard trade in ICT goods or e-commerce. Precisely if a choice needs to be made, I would argue for these flows to focus on in future policy negotiations.

Now, to focus which policies then: the OECD recently released an interesting report in which services trade by modes of supply are estimated. 

This is a huge step since before we only had a rough idea whether services trade took place through foreign affiliates after FDI was established (i.e. Mode 3), or through the internet (i.e. cross-border called Mode 1). The figure below shows both items in the form of a ratio: Mode 3 over Mode 1 in two points in time, namely 2000 (white dots) and 2014 (blue bars).

The figure tells me that the higher the blue bar, the more trade through establishments were important in 2010. When the blue bar falls below the white dot, trade over the internet has become more important over the years to 2014 – and vice versa.  

Source: Andrenelli et al. (2018), page 21; Analytical AMNE database Note: Exports of foreign affiliates have been removed from cross-border exports.

When looking at this figure, some extremely interesting conclusions become visible. One, for some services such as Distribution, Publishing activities, Computer and information services, and Financial and Insurance services, and possibly for Professional and Scientific services, this ratio decreased over time. 

This means that the internet as a vehicle for trade in these sectors has become more important. In other words, more trade of these sectors has been traded over the internet rather than through foreign establishments.

Other sectors such as Construction, Postal services, Warehousing and Transport support, Administrative services or even Telecom, trade through a foreign establishment has become more important over time as the blue bar falls above the white dots (though Telecom already had a high internet-trade ratio).

This pattern is very relevant to decide to focus on in terms of policy in services. The services sectors that have seen an increase of internet-based trade are also the ones that Ferracane et al. (2018) have assessed as very data-intensive. These are sectors that use a lot of software and data. These are also the sectors that are mostly affected by data-related policies such as data localization.

That’s visible in the figure below. The sectors which are colored in green are the ones which are most data-intensive; the sectors in red are least data-intensive. If a country has comparative advantage in data-intensive sectors, the policy restrictions covered by Cluster C in the DTRI are most relevant: data localization, data retention, intermediate liability and policies related to content access. 

Source: Author; Note: Data & Software intensities based on US Census data.

Conversely, if your country has comparative advantage in say Postal services, Transport, Health or Construction, then it makes sense for policy makers to focus on policies covered under Cluster B of Establishment restrictions. 

Sure, some trade in these sectors are still traded over the internet, but since complementarities exists between the two Modes of trade, prioritizing establishment restrictions will nonetheless have a knock-on effect on trade in these services over the internet.


Ultimately, therefore, choices on what policy to focus on will have to be based on your country’s comparative advantage: where is your country good at in exporting – and how it is traded.  

Ferracane, M., J. Kren and E. van der Marel (2018) “Do Data Policy Restrictions Impact the Productivity Performance of Firms?”, DTE ECIPE Working Paper Series No. 1, ECIPE, Brussels, forthcoming.

Thursday, 3 May 2018

Who is going to win the race for AI: China or US?

Who will win the race in Artificial Intelligence (AI)? Recent articles have focused on this big battle between China and the US. Arguments appear in favour of both countries. China has huge amounts of data and a more relaxed framework regarding privacy, whereas the US attracts a vast amount of talent to develop software computing and has the good climate to let digital firms with new ideas flourish.

Frankly, I think this issue is slightly more nuanced.

Arguments on both sides in favor of a strong AI based does not year, however, make clear who of the two will profit best from long-run economic benefits using AI. For instance, it is often pointed out that China has more data than the US and therefore would win the race. To me, it seems that both countries own large amount of data. And due to strong network effects, the fact of having large sets of data just simply points out that the focus is on these two countries, and not for instance on the EU. Hence, both can win.

The question who will reap greater long-run benefits from AI is a bit more complicated to answer. Who of the two will have sustainable specialization patterns in AI depends on what economists call comparative advantage. China may be big and therefore have large network effects in AI, but that does not yet mean comparative advantage. For that to determine, one needs to have a look at what sectors are most amenable to AI.

The figure below sets out the most AI-intensive sectors based on current usage of data and software out of a much wider range of industry and services sectors. The figure reveals some interesting insights. For instance, it shows that mainly services appear to be most open to AI such as internet and software services, finance and insurance, computer systems, and logistics. But a couple of manufacturing sectors are also stands out such as chemicals, motor vehicles, computer and electronics and electrical equipment. 

Source: author’s calculations; US Census; US BLS. 

Wednesday, 11 April 2018

Is your country boosting digital services exports?

A couple of weeks ago, together with my colleague Philipp Lamprecht, I presented a webinar on digital services trade. Digital services are the fastest growing component of all types of trade flows since 1995. The gap of growth between exports in digital services and in goods or traditional services has become bigger and bigger over the years.

What explains this observation? Well, some countries are just good at exporting digital services over the internet because of their friendly policies and good digital network environment. If you want to know who is good at exporting digital services, who is under-performing its potential, and why, then watch and listen to this webinar.


For instance, some countries, such as France and Germany, are laying behind their potential to export digital services while others, such as Romania and Ireland are leading in some digital services. Of course, some countries are naturally placed to export services. Yet some of them are precisely still under-performing in digital services relative to their potential.

The webinar explains all these issues. The webinar follows our work on digital services export that we did for the Bertelsmann Foundation. My co-authors were Philipp Lamprecht, Hanna Deringer and Fredrik Erixon. We plan to make a follow-up study to see more clearly what exactly drives this pattern.


Enjoy watching!

Thursday, 22 March 2018

Economic Impact of LCRs in BRICS at the WTO

Last week, ECIPE was invited at the WTO to speak on our work on local content requirements in BRICS countries. It was a great pleasure to be there, and the discussion I had with the WTO secretariat was a most interesting. See below for the slides.


Of note, this study takes a broader definition of LCRs into account in the sense that they can relate to public procurement, investments, business operations or market access. Yet in all cases they have a clear requirement for local content classifying them as an LCR. 

Happy read!

Wednesday, 28 February 2018

Supply chain complexity, ICT and trade

A recent McKinsey report notes that the intensity with which firms employ Information and Communication Technologies (ICT) depends on four factors: (1) size of the firm; (2) supply chain complexity; (3) skill levels inside the firm; and finally (4) threat of competition. 

Deployment of ICT facilitates reaches higher productivity levels inside the firm. The four determinants therefore seem reasonable as the firm-level literature shows that generally these four points are indeed factors that are strongly associated with greater firm performance. However, in my view, the second factor of supply chain complexity merits some elaboration and refinement, especially with regards to international trade.

It seems intuitive at first sight to think that ICT tools and instruments smoothen the supply chain network. And so, the more complex this network becomes the more this chain uses ICT to solve complex hold-up problems related to trade. This is because ICT allows for geographically dispersed production and management activities. However, the data tells something different: some supply chain trade, which requires greater ICT, may actually be related to lower supply chain complexity. 

This can be seen by a measure that computes the “length” of the value chain by accounting for the number of production stages (Fally, 2012). The more stages of production involved, the lengthier the chain becomes, the more complex one can assume the supply chain is. The figure below plots the average of this indicator of supply chain complexity across a like-minded set of OECD economies for each sector on the vertical axis. The horizontal axis plots the ICT-intensity indicator from van der Marel et al (2016) to see for any meaningful pattern.


Source: US BEA; OECD TiVA. Sector numbers follow ISIC Rev 3.

Thursday, 15 February 2018

FDI Screening: Implications for the Future

Two weeks ago, I spoke at an event where I commented on a very interesting paper from Copenhagen Economics (CE). The paper assesses the economics of EU Foreign Direct Investments (FDI) and the need to undertake screening in the EU. Economists are generally weary of setting up screening measures for foreign investments as it increases substantial costs for little economic reason.

Therefore, the recent proposal of the EC to introduce screening measures has more to do with political economy, wider geopolitical or even security reasons. For instance, one of the biggest concerns is that some of the recent FDI coming into the EU is from various emerging economies such as China, Kazakhstan and Russia, which still have many State-Owned Enterprises (SOEs) in their economies.

This according to economists is a problem, but a simple back-of-the-envelope calculation tells me that the share of this FDI in some sensitive sectors flowing from these countries with much SEOs involved is at most 3.5 percent of EU’s total incoming FDI. Hence, a first question appears: does that warrant an overall screening measure? Some trade-offs are involved as obviously economics doesn’t stand on its own here.

However, my intervention was about the future of foreign investments. In particular, the changing nature of investments the EU has received in recent years, namely investments in digital sectors. This should force policy makers to think about when proposing investment regulations, including screening.

First, although it is right to state that FDI brings along a great “footprint” as economist say, this is in fact much lower for digital investments. With “footprint” we mean economic activity such as employment, value-added and greater output. Footprints for tangible investments such as manufacturing are known to be high, but the recent UNCTAD (2017) report shows that this footprint from multinational digital companies is actually much lower.

This can be seen in the figure below that measures this footprint by taking the ratio from foreign sales over foreign assets. For manufacturing and telecoms this ratio is actually 1:1 (in case of telecoms the assets are high because of infrastructure investments). Yet for FDI coming from digital multinationals, foreign assets are typically lower leading to a much higher ratio (because of higher sales), which means a lower footprint.


Source: UNCTAD WIR (2017)

Thursday, 25 January 2018

LCRs versus tariffs: The see-saw of trade barriers?

You may have not noticed it, but the use of local content requirements (LCRs) has gone up for years. They are used by developed as well as developing countries. LCRs aim to promote the use of local inputs. They also serve the purpose of fostering domestic industries. BRICS and many other emerging countries are frequent users of LCRs, together with the US.

However, LCRs can be highly damaging for the economy. While LCRs might have the perceived benefit of creating industry activity and local employment, these gains or often generated in the short-term. LCRs are most likely to have a damaging economic impact that is wider in the long run. This harmful impact therefore evolves over time, which eventually outweighs any specific short run gain they can create.

ECIPE’s new study with undersigned contribution estimates the damaging impacts of LCRs for BRICS countries. Our team has translated their negative effects into so-called ad valorem equivalents (AVE). This is a methodological concept that allows one to readily compare the adverse impact of any non-tariff barrier (NTB) such as an LCR with a tariff. Our study has taken LCRs in the heavy vehicle sector as a case in point.

The results are presented in the figure below. They show that Brazil and Russia apply the most distortive LCRs for heavy vehicles. The two countries have an estimated increase of their import price of 15.6 and 11.1 percent respectively. China and South Africa both show low AVEs of 4.5 and 3.3 percent respectively. India’s LCRs are least harmful as it shows an AVE estimate of 2.2 percent.
 
Source: ECIPE calculations, based on ECIPE LCR BRICS database; WITS/UNCTAD TRAINS

Tuesday, 16 January 2018

Are services really not helping the economy?

Bullocks! That is the conclusion that came to me when I participated in the roundtable conference on services and economic development in Tokyo last month. This conference was organized by the Asian Development Bank Institute (ADBI) and discussed with experts the positive role of services in the world economy.

It’s high time for this discussion. In recent years there has been a slight backlash against services as a contributing factor to the economy, particularly for developing countries. One reason for this set-back against services stems from a recent article by Dani Rodrik in which he drives the point that many developing countries are de-industrializing faster than before and therefore moving into services too quickly.

This premature de-industrialization, he argues, prevents them from using the manufacturing sector as a tool for rapid economic growth. According to Rodrik, in large part this is due to globalization and trade itself because globalization has produced changes in relative prices in advanced countries. This can have serious negative consequences for developing countries’ growth potential because, in the future, they would be much less able to capitalize on manufacturing exports.

There are, however, a couple of remarks that in my view must be made here.

First, these conclusions are most probably based on aggregate figures between countries’ services and manufacturing activities, which in great part mask the fact that many manufacturing sectors have already become “servicified” to a high degree. This means that a lot of gains by manufacturing firms are earned though services, not manufacturing. For instance, is Zara a garment manufacturer nowadays or just a retailer? Most probably it comes close to the latter. Such servicification is not yet picked up and properly classified in aggregate figures – and this is true also for developing countries.

Second, there are surely economic meaningful sectors in a country’s services economy. The old way to look at services is that they don’t show a great economic role as they are not receptive to productivity improvements. That assertion seems to be out of date. Even though productivity for services is hard to measure, European micro-level data suggest that productivity varies hugely across services, and therefore their contribution to the overall economy is also varied. (see figure below). This should also be the case for non-developed economies.

Source: Data taken from Van der Marel, Kren and Iootty (2015) "Services in the European Union: What Kinds of Regulatory Policies Enhance Productivity?", World Bank Policy Research Working Paper No. 7919, World Bank, Washington DC.